For decades, Canadian real estate, especially in the Greater Toronto Area, seemed like a one-way bet. Recent years have been more complicated. Prices have softened in many markets, borrowing costs remain well above the ultra-low levels of 2020 and 2021, and governments have introduced new rules. So is property still a good investment? Here is a balanced look.
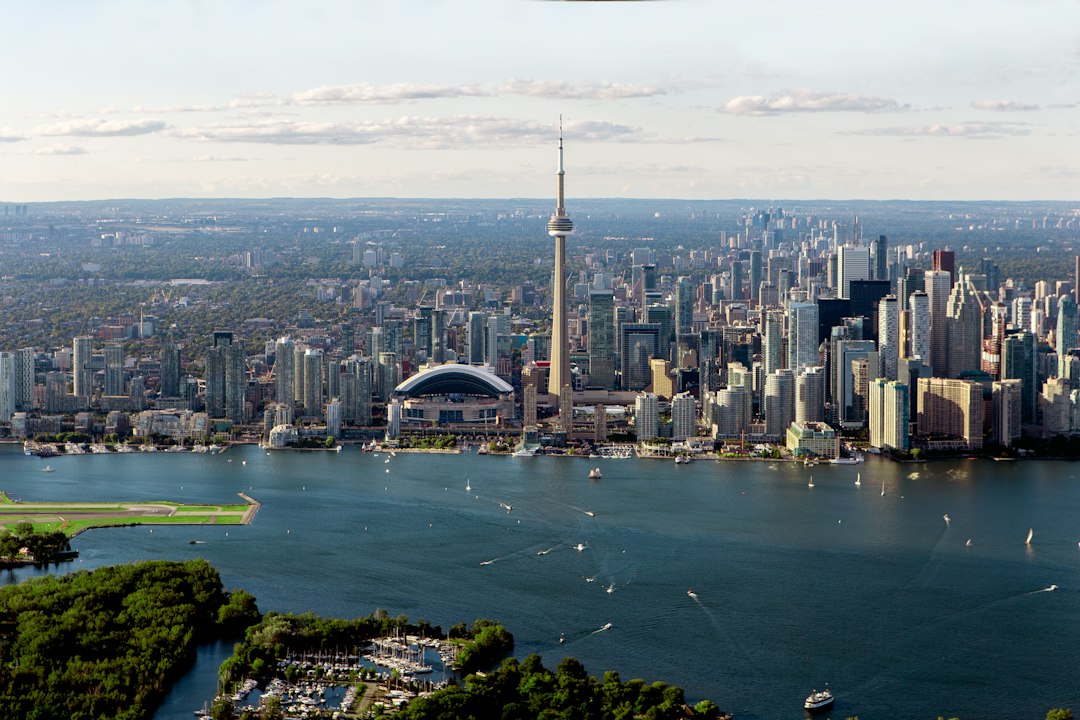
Where the GTA market stands
According to the Toronto Regional Real Estate Board (TRREB), GTA home sales in September 2026 totalled 5,040, down 9% from a year earlier. The average selling price was about $1,006,000, compared with roughly $1,060,000 in September 2025, and the composite benchmark price was down 4.7% year over year. New listings also fell by about 14%. Market watchers point to higher fixed mortgage rates, driven by rising bond yields, as a key reason buyers are cautious.
Reasons property can still make sense
- Long-term demand: Canada’s population continues to grow, and the GTA remains a major destination for newcomers and jobs.
- Limited supply: despite more listings recently, building enough housing remains a long-term challenge.
- Forced savings: mortgage payments build equity over time.
- Buying opportunities: a softer market gives buyers more choice and negotiating power than in peak years.
Risks to weigh
- Interest rates: payments at renewal can rise sharply. Make sure you could handle higher rates.
- Cash flow: in many GTA markets, especially condos, rents may not cover the mortgage, taxes, condo fees and maintenance of an investment property.
- Vacancies and tenant issues: Ontario’s residential tenancy rules give tenants strong protections, and disputes at the Landlord and Tenant Board can take time.
- Taxes and rules: rental income is taxable, capital gains apply to investment properties, and the federal anti-flipping rule taxes profits on homes sold within 12 months as business income in most cases.
Rules that affect buyers
- Non-Canadians are restricted from buying residential property under the federal foreign buyer ban, which has been extended into 2027.
- Ontario charges a Non-Resident Speculation Tax of 25% on foreign buyers.
- First-time buyers can save up to $8,000 per year (lifetime limit $40,000) in a tax-free First Home Savings Account (FHSA).
Alternatives to buying property directly
Real estate investment trusts (REITs) and real estate ETFs offer exposure to property with more liquidity and lower minimum investments, though they come with market volatility.
How to decide
- Run the numbers with realistic rates, vacancies and maintenance costs. Our mortgage calculator guide can help.
- Keep an emergency fund separate from your down payment.
- Think in terms of 10 years or more, not quick gains.
- Get advice from a licensed financial advisor, accountant and real estate lawyer.
Follow local trends in our Toronto Housing Market Outlook 2026 and the Real Estate section.
Sources: TRREB Market Watch, September 2026; Government of Canada. This article is general information, not financial advice.



Comments are off for this post.